Search Is Fragmenting Across Engines and LLMs
Search now happens across Google, Bing, AI features inside those engines, and standalone assistants such as ChatGPT. Customers can research, compare, and narrow their choices before visiting a website. Search still produces enormous demand and measurable enrollments, but a provider’s influence may begin well before the first recorded click. That changes what visibility and acquisition performance mean.
Search has more places to start and more ways to finish
Google remains the largest search engine by a considerable margin. It has said it handles more than 5 trillion searches a year. At the same time, AI is now part of Google’s own search experience: the company says AI Overviews reaches more than 2.5 billion monthly users and AI Mode more than 1 billion. OpenAI reported more than 1 billion weekly active ChatGPT users in August 2026. These are company disclosures about different activities, not a market share comparison. A search, a weekly user, a monthly user, and a website visit don’t belong in the same denominator. [1][2]
Independent consumer research confirms that assistants have become an information source. In a February 2026 Pew Research Center survey, 49% of U.S. adults said they use AI chatbots and 42% said they use them to search for information. That does not mean 42% of searches occur in chatbots. It does mean a sizable audience is willing to ask questions away from the familiar search results page. [3]
And the AI audience isn’t confined to one assistant. Similarweb’s worldwide web panel showed ChatGPT’s share of visits to generative AI websites at roughly 53% in May 2026, down from about 76% a year earlier as Gemini and Claude gained share. This measures visits to those sites, not use inside mobile apps or Google’s AI features in Search. A brand’s visibility in one assistant cannot stand in for its visibility everywhere customers ask questions. [4]
The question has changed along with the destination
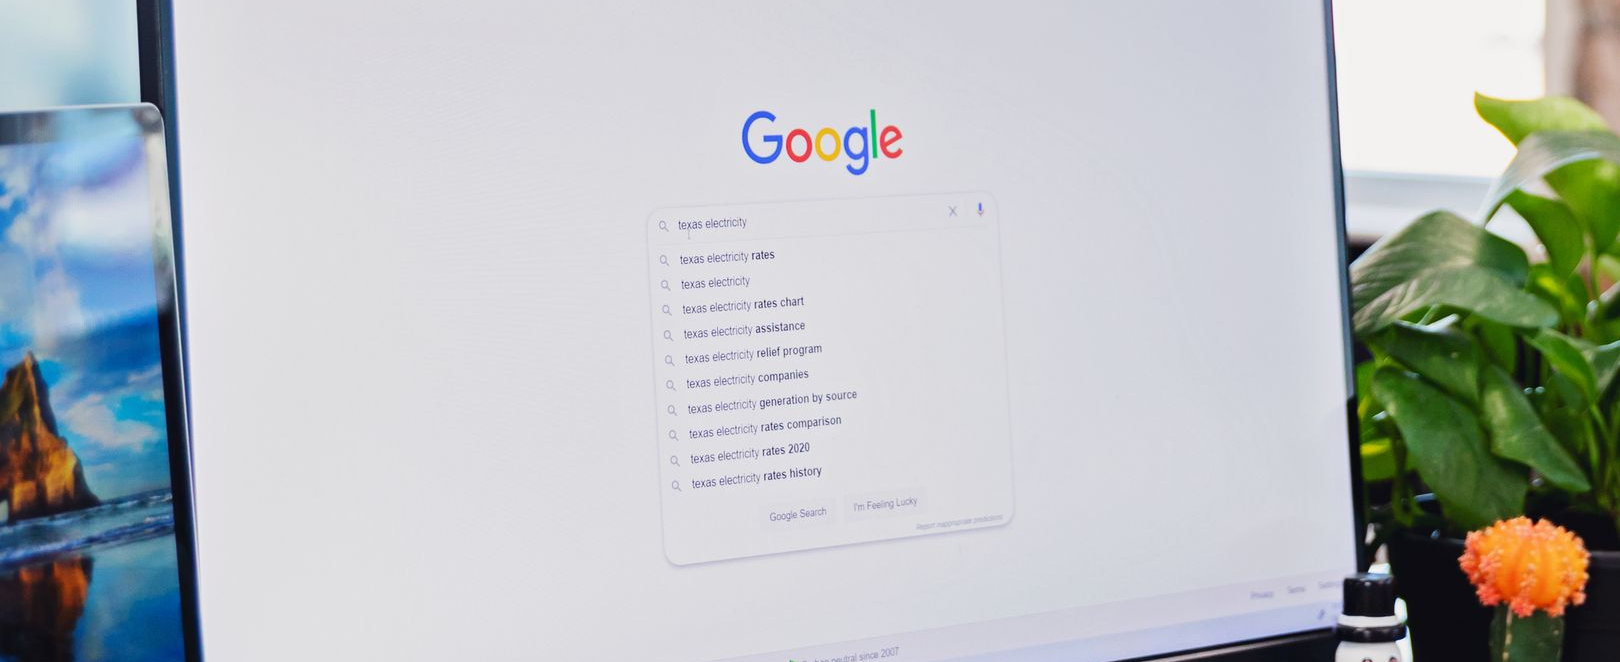
Consider the difference between typing “Texas electricity rates” and asking, “I’m moving to Houston, work from home, use about 1,400 kWh a month, and want a fixed price without a bill credit that disappears at lower usage. What should I compare?” The second request supplies a location, usage pattern, preference, and exclusion. A useful answer has to explain several pieces of the decision before a plan is selected.
Google says the average AI Mode query is three times as long as a traditional Search query. Its AI features can break a question into related searches across subtopics and data sources, then assemble a response with links. Microsoft’s Copilot Search in Bing similarly presents summarized answers, cited sources, and follow-up exploration. A customer may now refine the question inside the platform rather than open five tabs to do the same work. [5][6]
Someone who knows a provider’s name, needs to pay a bill, wants an outage number, or is ready to enter a ZIP code may still use a short search and click directly. The shift is most consequential when the customer needs explanation, comparison, or help defining the right choice.
Visibility and website traffic are separating
A provider can be seen without receiving a visit. The brand may appear in an AI answer, be cited as a source, or be included in a shortlist that a customer carries into a later branded search. Those are different outcomes. A citation doesn’t prove the assistant recommended the provider, and a mention doesn’t prove the customer noticed it. But neither outcome appears reliably as a referral session in ordinary site analytics.
Pew’s browsing study of 900 U.S. adults found that people clicked a traditional result in 8% of Google visits that showed an AI summary, compared with 15% of visits without one. They clicked a source link within the summary in 1% of visits with a summary. Those are observational results from searches conducted in March 2025, not a controlled estimate that AI summaries caused the entire difference. Query types differ, and the study cannot tell us the conversion value of the clicks that remain. It does show why an appearance in an answer cannot be valued as though it were a website visit. [7]
Clicks still matter, and AI tools are sending more of them. Similarweb estimates that AI platforms generated an average of 770.7 million referral visits a month worldwide from June 2025 through May 2026, up 117.4% from the preceding period. It also says those referrals remain a low single-digit share of total traffic for most sites. The two observations can coexist: a channel can grow quickly from a small base while much of its influence stays inside the platform. [8]
Referral quality varies too. In Adobe’s May 2026 U.S. data, AI-referred retail visits converted 54% better than non-AI visits, while AI-referred travel visits converted 28% worse, despite stronger on-site engagement. Those figures describe Adobe’s observed categories and time period. They are not an electricity enrollment benchmark. They show why a provider should care about the outcome of a visit, not merely the traffic source printed beside it. [9]
Query intent matters more than an industry-wide AI average
AI exposure doesn’t rise uniformly across every search. In one BrightEdge sample of finance queries, AI Overviews appeared on 91% of educational queries, 67% of rate and planning queries, and 7% of stock ticker and real-time price queries. BrightEdge’s healthcare analysis likewise found substantially more AI treatment of explanatory clinical topics than of local provider searches. Those percentages belong to its tracked keyword sets, not to all Google searches or to retail energy. They illustrate a useful distinction between questions that need synthesis and requests that need a current figure, a specific destination, or a direct action. [10]
For an electricity provider, “How does a bill credit work at 500 versus 1,000 kWh?” and “Which plan can I enroll in at this address today?” are related questions with different information needs. The first invites explanation. The second depends on service area, current offer details, eligibility, and an enrollment path. AI can take part in either journey, but the role it plays may differ sharply.
Search measurement needs to account for what it cannot see
The familiar acquisition report begins when a person arrives on a site. The research that shaped that arrival may be invisible. A customer could ask an assistant to compare plan types, read an AI Overview about early termination fees, then type a provider’s name into Google and enroll. Site analytics may assign credit to branded organic search or direct traffic. That is a correct description of the recorded visit and an incomplete description of the decision.
First-touch and last-touch attribution both have this limitation. Better event collection can make observed sessions and enrollments more reliable, but it cannot recover an impression or conversation that never generated a visit. Nor should every increase in branded search or direct traffic be attributed to AI. Advertising, offline exposure, word of mouth, and normal demand shifts can produce the same pattern. The appropriate conclusion is narrower: the channels that close demand and the experiences that create or shape it can no longer be assumed to be the same.
There are now three distinct questions for an acquisition team:
- Visibility: Is the provider named, accurately described, or cited when people research the topics and decisions that matter to it?
- Traffic: Which engines and assistants actually send visits, and which pages do those visitors reach?
- Business effect: Do those visitors become qualified enrollments, valuable customers, or lower-cost customers to serve, and is there evidence that broader visibility changes demand beyond attributed clicks?
The data sources answer different parts of this picture. Google has introduced a Generative AI performance report in Search Console for appearances in its AI features, and Bing Webmaster Tools has an AI Performance dashboard with citation and grounding-query data. Neither is a universal ledger of every assistant’s answers. Third-party prompt sampling can reveal patterns, but answers may vary by wording, location, user context, timing, and product surface. A mention count is a diagnostic measure, not a substitute for enrollments or incrementality. [11][12]
Paid visibility is fragmenting too
The new interfaces are also advertising surfaces. Google says eligible Search, Shopping, and Performance Max ads can appear within AI Overviews in supported markets, but advertisers cannot target only those placements or get a separate within-Overview performance segment. Google also excludes sensitive verticals, including finance and healthcare, from ads inside AI Overviews. A retail electricity advertiser should not assume that another industry’s placement or result applies to its own offers. [13]
OpenAI says ChatGPT Ads are available in more than 40 countries and that ads are labeled separately from ChatGPT’s answers. It reports more than 1 billion weekly active ChatGPT users, but that figure is the service’s audience, not the reach or performance of any advertiser’s campaign. As more commercial placements develop, providers will have to judge them by eligible reach, control, lead quality, and enrollment economics rather than by the novelty of the surface. [14]
What this means for retail energy providers
Retail electricity is unusually vulnerable to a confident but incomplete answer. A plan can look attractive at a displayed usage level and behave differently at the customer’s actual consumption. Bill credits, minimum usage rules, time-of-use terms, contract length, early termination fees, renewable claims, and delivery charges all affect the decision. In Texas, the Public Utility Commission describes the Electricity Facts Label as the document that sets out price and contract information, and its Power to Choose site lets shoppers compare posted offers. A provider’s offer also depends on where the customer takes service. [15]
Acquisition starts before the rate table
A shopper may reach a shortlist before visiting a provider’s plan page. If an assistant explains a free nights plan without addressing daytime usage, or treats a bill-credit average price as a universal rate, it can shape an unrealistic expectation. If it overlooks a provider altogether, the provider may never get the chance to present its offer. The business question is whether customers encounter an accurate account of the plans and tradeoffs while they are still forming their criteria.
That matters across SEO and paid media. Transactional searches for rates, plans, and providers remain valuable, particularly when a customer is ready to check availability and enroll. Explanatory questions can influence which provider enters that final comparison. A strong search presence therefore has to support both the decision to consider a provider and the decision to complete an enrollment. The relative value will vary by market, product, and customer segment.
Enrollment quality may be a bigger prize than an extra visit
An informed customer can be more valuable than a merely persuaded one. Consider someone comparing a time-of-use plan with a conventional fixed-rate plan. If the customer understands when usage must shift for the first plan to pay off, the resulting enrollment has a better chance of matching the household’s needs. The same reasoning applies to EV charging patterns, bill-credit thresholds, deposits, and term commitments. This is a business hypothesis to test, not a published claim that AI-referred electricity customers retain better.
Poor explanations create the opposite risk. A customer who enrolls based on an oversimplified monthly cost may call when the first bill differs, dispute the offer, switch sooner, or leave a negative review. Those costs sit outside the initial cost-per-acquisition figure. As AI increasingly participates in comparison, the accuracy of what customers encounter before enrollment becomes part of acquisition quality and cost to serve.
Retention and customer value belong in the same discussion
Search doesn’t end at enrollment. Customers ask why a bill changed, how an indexed or time-of-use plan works, when a contract expires, or what happens during an outage. The answers they find may come from a search engine, an assistant, a comparison site, a regulator, or the provider itself. A clear explanation can help a customer resolve a question. An incomplete one can send them into a call queue or make a competing offer look simpler than it is.
That makes search fragmentation a customer lifecycle issue. A provider may win the click and lose the expectation, or miss the initial click and still influence a later enrollment. The sensible executive view holds both outcomes in sight: traditional search traffic and conversion remain essential, while answer visibility and the quality of the information behind it deserve their own scrutiny.
The decision is where to place confidence
No public dataset can turn searches, assistant prompts, answer appearances, and enrollments into one clean market-share number. No citation dashboard can prove how many customers an answer persuaded. Yet the evidence is strong enough to change the questions leaders ask. Where do customers form their shortlist? Which explanations shape their expectations? What portion of measurable demand is arriving after research elsewhere? And are the customers acquired through these paths worth more after the first bill?
Providers that answer those questions carefully can make better decisions about content, media, measurement, and the enrollment experience. Search is still a major source of customers. Its influence now extends well beyond the click that shows up in a channel report.
Sources and Notes
- Google, More opportunities for your business on Google Search states the annual search figure. Google, New opportunities, control and insights for website owners gives AI Overviews and AI Mode monthly user figures, updated August 31, 2026. The user groups overlap.
- OpenAI, A milestone in expanding access to AI, August 31, 2026, gives the weekly active user figure. Weekly users are not searches or prompts.
- Pew Research Center, Americans and AI 2026, survey conducted February 17 to 23, 2026. Its 42% measure is the share of U.S. adults who report using chatbots to search for information.
- Similarweb, AI Search Stats 2026, worldwide generative AI website traffic through May 2026. Website visits exclude substantial app and embedded use.
- Google, How AI Mode is changing and expanding the way people search and Google Search Central, AI features and your website. The latter explains query fan-out and the role of supporting links.
- Microsoft Bing, Copilot Search describes summarized answers, cited sources, and follow-up exploration.
- Pew Research Center, Google users are less likely to click on links when an AI summary appears. Browsing panel of 900 U.S. adults; search behavior from March 2025, with result pages collected in April.
- Similarweb, AI Referral Traffic by Industry, September 3, 2026. Its global estimates cover desktop and mobile web referrals, June 2025 through May 2026.
- Adobe Digital Insights, AI travel traffic nearly triples in May 2026. Retail and travel conversion comparisons refer to Adobe's observed U.S. site traffic in May 2026.
- BrightEdge, Finance and AI Overviews and Healthcare and AI Overviews. These are tracked keyword samples with category-specific definitions.
- Google Search Central, Guide to optimizing for generative AI features describes the Generative AI performance report. Google's rollout notice says the new controls and insights were available to websites worldwide as of August 31, 2026.
- Microsoft Advertising, See how you're showing up in AI search describes Bing Webmaster Tools' citation, page, and grounding-query measures.
- Google Ads Help, About ads and AI Overviews gives current placement eligibility, exclusions, and reporting limits.
- OpenAI, A milestone in expanding access to AI describes ChatGPT Ads' reach, availability, and separation from answers as of August 31, 2026.
- Public Utility Commission of Texas, Electricity Facts Labels for Residential Electric Service and Power to Choose describe plan disclosures and the official Texas comparison site. The retail energy examples in the article are illustrative, not a measured industry study.